
Why is Toledo so cheap? Population loss, lower incomes, older homes and high taxes kept...
Read More
If you're buying Toledo rentals with a full-time job in another state, a self-employed income, or a growing portfolio, a conventional mortgage gets harder with every property. A DSCR loan in Ohio solves that by qualifying the rental on its own rent instead of your tax returns. But Toledo's low prices create problems most DSCR guides don't mention, like loan minimums that are bigger than the house. This DSCR loan Ohio guide explains how the ratio is calculated on a real Toledo rental, what lenders are charging in October 2026, when DSCR beats a conventional or hard-money loan, how it fits a BRRRR refinance, and what changes for 5+ unit apartment buildings.
The short answer
A DSCR (debt service coverage ratio) loan qualifies an Ohio rental by dividing its monthly rent by its monthly payment, including principal, interest, taxes and insurance. Most lenders want a ratio of 1.0 to 1.25 or higher, 20% to 25% down, and a credit score of about 620 to 680+. In fall 2026, typical 30-year DSCR rates ran roughly 6.75% to 8% for clean files, with smaller loans priced higher. Toledo's catch: many DSCR lenders won't make loans under $75,000 to $100,000, so cheaper houses often need a different plan, such as buying with cash and refinancing several at once, or using a local bank.
1.0–1.25
Minimum DSCR most lenders require
Published lender guidelines, 2026
20%–25%
Typical down payment (75%–80% LTV)
Published lender guidelines, 2026
$75K+
Common minimum loan amount, a real limit in Toledo
Lender guidelines and investor forums
1.30
DSCR on a typical $120,000 Toledo rental at $1,250 rent, 8% rate
Our calculation
What a DSCR Loan Is (and Who It's For)
A DSCR loan is a non-QM investment property mortgage that underwrites the rental instead of the borrower. There's no debt-to-income ratio and usually no tax returns or W-2s. The lender looks at the property's rent, the payment, your credit score, your down payment and your cash reserves. Most DSCR lenders also let you close in an LLC, which many investors prefer (our guide to an LLC for rental property in Ohio covers the trade-offs).
A DSCR loan in Ohio is a good fit if you:
- Are self-employed or have income that looks low on tax returns after write-offs
- Already have several financed properties and are hitting conventional loan limits
- Want to buy in an LLC
- Are refinancing out of a hard-money loan after a BRRRR rehab
It's usually not the cheapest option if you have strong W-2 income and fewer than a handful of mortgages. A conventional investment loan often prices better in that case.
How a DSCR Loan in Ohio Is Calculated: A Toledo Example
DSCR = monthly rent ÷ monthly PITIA (principal, interest, taxes, insurance and any HOA dues). Lenders typically use the lower of the signed lease or the appraiser's market rent schedule (Fannie Mae Form 1007). Here's a typical Toledo three-bedroom:
| Line | Amount |
|---|---|
| Purchase price | $120,000 |
| Loan (75% LTV) | $90,000 |
| Rate (30-year fixed, illustrative) | 8.00% |
| Principal and interest | $660 |
| Property tax (Toledo City SD, about 2.0% of value) | $201 |
| Landlord insurance | $100 |
| PITIA | $961 |
| Market rent | $1,250 |
| DSCR (1,250 ÷ 961) | 1.30 |
At 1.30, this house clears almost every DSCR lender's minimum. Working backward, the same house supports a loan of about $95,000 at a 1.25 DSCR or about $129,000 at 1.0 (though no lender would go above its maximum loan-to-value).
DSCR is not cash flow. The lender's ratio ignores vacancy, property management, repairs and capital reserves. This same house has about $530 a month of net operating income after real expenses, so with a $660 principal-and-interest payment it actually runs about $130 a month negative. Qualifying for a DSCR loan doesn't mean the deal works. Our breakdown of the cost of owning a rental property in Toledo shows every expense.
DSCR Loan Ohio Terms in 2026
| Term | Typical range (fall 2026) | Notes |
|---|---|---|
| Minimum DSCR | 1.0 to 1.25 (some programs 0.75 or "no ratio") | Lower ratios cost more and need more down |
| Down payment / LTV | 20% to 25% down (75%–80% LTV) on purchases | Cash-out refinances usually cap at 70%–75% LTV |
| Credit score | 620 to 680 minimum; 720+ gets the best pricing | Varies widely by lender |
| 30-year fixed rate | About 6.75% to 8% for clean files | A September 2026 survey put typical quotes at 6.125%–7.375%; rates rose in October |
| Small-loan pricing | About 1 to 1.5 points higher under ~$200,000 | Fixed costs weigh more on small loans |
| Points and fees | 0 to 3 points, plus lender and underwriting fees | Compare total cost, not just the rate |
| Prepayment penalty | Commonly 3-2-1 or 5-4-3-2-1 years | Shorter penalties usually mean a slightly higher rate |
| Reserves | Often 3 to 6 months of PITIA | More for larger portfolios |
| Vesting | Personal name or LLC | Personal guarantee usually required |
Ranges compiled from published lender guidelines and rate surveys (see sources). For comparison, Freddie Mac's 30-year average for owner-occupied loans was 7.32% on October 22, 2026, up from 6.19% a year earlier. Rates change daily; get written quotes.
About prepayment penalties: a 5-4-3-2-1 penalty charges 5% of the balance if you pay off in year one, stepping down to 1% in year five. If you think you might sell or refinance within three years, a shorter 3-2-1 penalty (or none, at a higher rate) is usually worth the extra cost.
The Toledo Problem: Minimum Loan Amounts
Here's the issue national DSCR guides don't cover. Many DSCR lenders set a minimum loan amount of $75,000 to $100,000, and a few go down to about $50,000 to $55,000, usually with higher pricing and a minimum fee that can run several thousand dollars. In Toledo, where plenty of solid rentals sell for $60,000 to $90,000, that's a real problem:
| Purchase price | 75% loan | Meets a $75,000 minimum? |
|---|---|---|
| $70,000 | $52,500 | No |
| $90,000 | $67,500 | No |
| $100,000 | $75,000 | Just |
| $120,000 | $90,000 | Yes |
How Toledo investors work around it:
- Buy cheaper houses with cash, then refinance several at once with a blanket or portfolio DSCR loan that combines them into one larger loan.
- Use a local bank or credit union. Toledo-area community lenders are often more flexible on small loans, though they usually want shorter terms and may look at your income too.
- Buy duplexes or small multifamily. A $110,000 duplex clears the minimum where a $70,000 house doesn't, and often cash flows better.
- Plan the BRRRR refinance on after-repair value. A house bought for $60,000 and worth $135,000 after rehab can support a loan above the minimum.
Financing a Toledo Rental From Out of State?
Austin works with investors who use DSCR, conventional and local bank financing, and can help you find Toledo properties that fit your lender's minimums and DSCR before you make an offer.
Talk to Austin About Financing-Ready DealsNo pressure. No obligation.
DSCR vs. Conventional vs. Hard Money vs. Local Bank
| DSCR loan | Conventional investment loan | Hard money | Local bank / credit union | |
|---|---|---|---|---|
| Qualifies on | Property rent | Your income and debts | The deal and after-repair value | You and the property |
| Down payment | 20%–25% | 15% (1 unit), 25% (2–4 units) | 10%–20% plus some rehab | 20%–30% |
| Rate (fall 2026) | About 6.75%–8%+ | Above owner-occupied rates | Often 10%–13% plus points | Varies; often adjustable |
| Term | 30-year fixed available | 30-year fixed | 6–18 months | Often 5-year fixed, 20–25-year amortization |
| LLC ownership | Yes | No (personal name) | Yes | Usually yes |
| Property limit | None | Up to 10 financed properties | None | Lender's appetite |
| Best for | Self-employed, larger portfolios, LLCs, BRRRR refis | Strong W-2 income, first few rentals | Buying and rehabbing distressed homes | Small loans, 5+ units, relationship lending |
Typical ranges, not quotes. Conventional limits per Fannie Mae eligibility rules; more financed properties require higher credit scores and reserves.
For a fuller look at out-of-state financing options, see our guide to financing a rental property out of state.
Using a DSCR Loan for a BRRRR Refinance
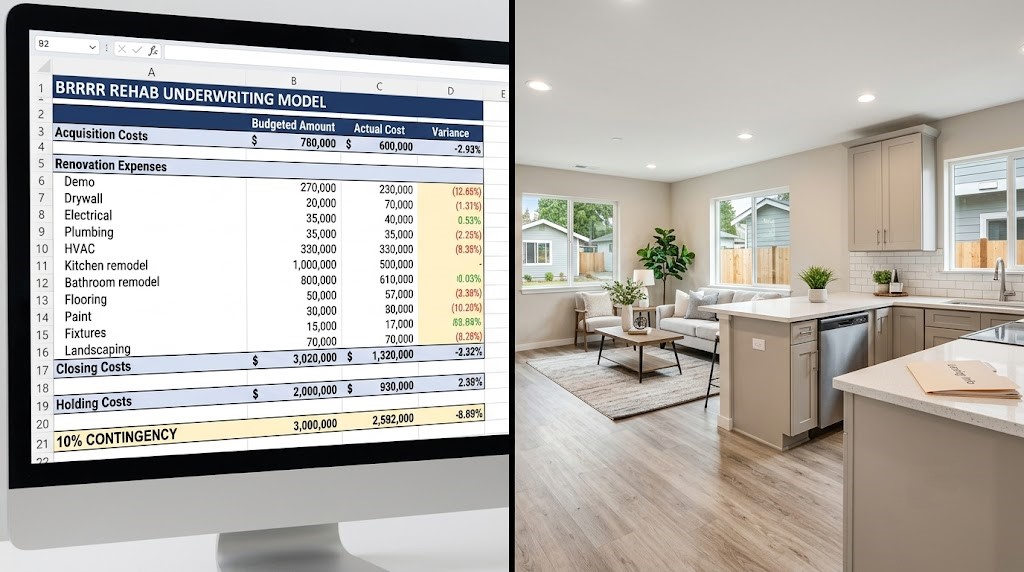
DSCR loans became the default BRRRR refinance for many investors because they don't require your income, and many allow a cash-out refinance after a short ownership period. Here's how a Toledo BRRRR refinance can look:
| Step | Amount |
|---|---|
| Purchase (cash or hard money) | $60,000 |
| Rehab, lead-safe work and holding costs | $35,000 |
| All-in cost | $95,000 |
| After-repair value (appraisal) | $135,000 |
| DSCR cash-out loan at 75% LTV | $101,250 |
| PITIA at 8.25% (P&I $761 + tax $226 + insurance $110) | $1,097 |
| Rent after rehab | $1,300 |
| DSCR | 1.19 |
| Cash left in the deal | about $0 (all cash returned, before closing costs) |
What to confirm before you buy, not after the rehab:
- Seasoning: some DSCR lenders will refinance on the appraised value after about three months of ownership; others require six months or more, or cap the loan at your cost until then.
- Appraisal risk: Toledo comparable sales can vary a lot block to block. Get a realistic ARV from recent renovated sales on the same street, not the whole ZIP.
- DSCR on the refinance: at 8%+ rates, the cash-out loan above only reaches 1.19. Check the lender's minimum before you assume you'll pull all your cash out.
- Conventional alternative: if you bought with all cash, Fannie Mae's "delayed financing" exception can allow a conventional cash-out soon after purchase, generally limited to what you paid plus closing costs.
More on the full strategy in our Toledo BRRRR playbook, and you can test numbers in the BRRRR calculator.
Financing 5+ Unit Apartment Buildings in Toledo
Once a building has five or more units, it's a commercial loan, and the rules change:
- Agency small-balance lending moved up-market. Freddie Mac folded its small-balance program into its conventional platform in April 2026, and its small product now starts at about $2 million. Fannie Mae's small loan program still exists, but most Toledo 5–20 unit buildings trade well below those sizes.
- Local banks and credit unions do most small Toledo apartment loans. Typical structures: 20%–30% down, a 5-year fixed rate with a 20- to 25-year amortization, and a minimum DSCR of about 1.20 to 1.25 based on the building's actual operating statement.
- At today's rates, DSCR often limits the loan, not the LTV.
| Example: 8-unit building, Toledo (43612) | Amount |
|---|---|
| Asking price | $650,000 |
| Gross rent (8 × $850 × 12) | $81,600 |
| NOI at a 50% expense ratio | $40,800 (6.3% cap rate) |
| Loan at 75% LTV, 7.5%, 25-year amortization | $487,500; $43,231 a year |
| DSCR at 75% LTV | 0.94 (doesn't qualify) |
| Maximum loan at a 1.25 DSCR | about $368,000 (57% LTV) |
| Down payment actually needed | about $282,000 |
Illustration based on an 8-unit Toledo listing in October 2026 with 2-bedroom units. Rents and expenses are assumptions; the actual rent roll and operating statement drive any real loan.
That's the reality for small apartment buildings in 2026: unless the price comes down or rents go up, buyers need much more cash than the advertised "25% down." It's also why Toledo apartment cap rates of about 4.7% to 5.7% are hard to finance at today's rates. Our Toledo cap rates guide compares property types.
How to Choose a DSCR Lender
- Minimum loan amount and minimum property value, in writing, before you shop for houses
- How they calculate rent: lease, appraiser's market rent, or the lower of the two
- Minimum DSCR, and how pricing changes at 1.0, 1.15 and 1.25
- Total cost: rate, points, lender fees and any minimum fee on small loans
- Prepayment penalty options and their rate difference
- Seasoning rules for cash-out refinances
- Whether they lend in LLCs and require a personal guarantee
- Experience with Ohio appraisals on lower-priced homes
- Reserve requirements across your whole portfolio
Get at least three written quotes on the same scenario. The cheapest headline rate is often not the cheapest loan once points and fees are added.
FAQ
What is the minimum DSCR for a loan in Ohio?
Most DSCR lenders want a ratio of at least 1.0 to 1.25, meaning the rent covers the full monthly payment including taxes and insurance. Some programs accept ratios as low as 0.75 or have no minimum, but they charge higher rates and require more down. A typical $120,000 Toledo rental renting for $1,250 has a DSCR of about 1.30 at an 8% rate.
How much down payment do I need for a DSCR loan?
Usually 20% to 25% on a purchase, meaning a 75% to 80% loan-to-value ratio, plus closing costs and reserves of about three to six months of payments. Cash-out refinances typically cap at 70% to 75% of the appraised value. Weaker credit or a lower DSCR can require a larger down payment.
What are DSCR loan rates in 2026?
In fall 2026, typical 30-year fixed DSCR quotes for strong files ran roughly 6.75% to 8%, after a September survey showed 6.125% to 7.375% and rates rose in October. Loans under about $200,000 often price 1 to 1.5 points higher. Rates depend on credit, DSCR, loan-to-value, points and the prepayment penalty you choose.
Can I get a DSCR loan on a cheap house in Toledo?
Sometimes, but many DSCR lenders have minimum loan amounts of $75,000 to $100,000, so a $70,000 house with 25% down falls short. Toledo investors often buy cheaper houses with cash and refinance several together, use a local bank or credit union, buy duplexes that clear the minimum, or refinance on the after-repair value after a rehab.
Can I use a DSCR loan for a BRRRR refinance?
Yes. DSCR loans are a common BRRRR refinance because they don't require your income. Many lenders allow a cash-out refinance based on the appraised value after a few months of ownership, typically up to 70% to 75% of value. Check the lender's seasoning rules, minimum DSCR and loan minimums before you buy the property.
Do DSCR loans allow LLCs in Ohio?
Most DSCR lenders allow you to close in an LLC, which conventional mortgages generally don't. Lenders usually require a personal guarantee from the LLC's members, and some require the LLC to be formed before closing. Ask your attorney or CPA whether an LLC makes sense for your situation.
The right loan depends on the property you buy, and the right property depends on the loan you can get. Austin helps investors line those up from the start, so the house you fall in love with is one your lender will actually finance. See our Toledo ROI calculator to run your own numbers.
Talk to Austin About a Toledo Deal
Disclaimer: Austin Cleghorn is a Realtor, not a mortgage lender or loan originator. Rates, terms and program rules in this article are general ranges from public sources as of October 2026 and change daily. This isn't a loan offer, rate quote or financial advice. Get written quotes from licensed lenders.
Sources reviewed for this guide (October 2026)
- Freddie Mac 30-year fixed mortgage rate (FRED)
- Norada: DSCR loan rate survey (September 2026)
- HomeAbroad: DSCR loan interest rates
- RentalRealEstate.com: DSCR loans (updated April 2026)
- BiggerPockets: Frequently asked questions about DSCR loans
- LendFriend: DSCR loan prepayment penalties
- Kiavi: DSCR loans for BRRRR refinances
- Amerisave: Delayed financing explained
- Fannie Mae Selling Guide: Multiple financed properties
- Multifamily.loans: Freddie Mac small-balance changes (April 2026)
- Redfin: Toledo multifamily listings (October 2026)


